As the final moments of a thrilling Copa Libertadores match tick away, the atmosphere in the stadium grows electric. A critical moment arises when the ball strikes an outstretched arm, leading the referee to award a penalty. Fans are on the edge of their seats, yet amid the excitement, a new bettor rushes to place a wager before the decisive kick. Just as they confirm their bet and approach the cashier, they abruptly stop; their preferred payment method is not available, and they lack a credit card. The goal is scored, but the betting opportunity vanishes in seconds.
This scenario serves as a stark reminder of the challenges faced by betting operators in Latin America. Abandoned transactions cost them not just revenues but also wasted marketing investments and diminished conversion rates. To thrive in this burgeoning market, it's essential for operators to eliminate payment barriers during this crucial stage of the customer experience.
The forecast for the Latin American iGaming market is promising, with projections suggesting it could approach $10 billion by 2028. The region is witnessing the emergence of regulated markets, improved connectivity, and a faster adoption of mobile technology. Coupled with a large base of sports enthusiasts, this development is engaging both domestic and international operators.
In spite of this growth, a significant remnant of the past—cash—still dominates. The Worldpay global payments report indicates that in 2025, cash transactions constituted 23% of point-of-sale spending in the region, which is notably 9% higher than the global average. Variations exist within the region; while Brazil (12%) and Chile (16%) align with global trends in cash usage, Colombia (32%) and Mexico (40%) are much more reliant on cash transactions. Additionally, a striking 26% of the Latin American population is unbanked, accentuating the need for betting operators to offer payment options that cater to local financial habits.
Innovative technology holds potential solutions. Regulatory reforms are invigorating the fintech landscape in Latin America. Brazil exemplifies this evolution, as noted by Ari Célia, co-founder and director of Pay4Fun. “Digital bank accounts in Brazil are common and easy to open. You just download an app,” he states, adding that “even if you have a bad credit record, you can still get a bank account.”
Pix, a digital payment solution overseen by the Brazilian Central Bank, has become immensely popular, reportedly facilitating 96% of gambling transactions in Brazil according to Pay4Fun’s data. This showcases how embracing local payment solutions can draw in previously underserved customers.
In Chile, formal financial systems are widely adopted, partly due to the country's stable economy compared to nations like Argentina. This has led to a high percentage of banked consumers, with debit and prepaid cards representing 32% of online payments. However, trust patterns vary significantly across Latin America. Mónica De Martino, a senior leader in payment solutions, articulates that many Mexicans are apprehensive about government oversight regarding their financial transactions. In Mexico, where many jobs are informal and paid in cash, this hesitation is compounded.
The use of cash is particularly predominant in daily transactions; it's the linchpin for payments ranging from public transport to small retail purchases. Furthermore, limited financial literacy can be a barrier to entering the formal banking system, as many individuals lack a thorough understanding of how bank accounts operate. Unexpected fees and complexities deter them from embracing banking services.
Célia underscores the immediacy required in today’s betting environment, explaining that while users once accepted delays, “now players get upset if it takes more than 10 seconds to confirm Pix.” Traditional banking struggles with delays, failed transactions, and rejected cards present ongoing challenges.
To capture and retain players effectively, operators must grasp the specific pain points of each market. In Argentina, Célia remarks that historical hyperinflation complexities have deterred international payment companies, driving players to seek alternatives for preserving their funds. Digital wallets like Mercado Pago enable users to earn returns on their balances while conveniently accessing funds for daily transactions.
The buy now, pay later model is also gaining traction in Argentina, with its market projected to reach $6.19 billion by 2030, aided by platforms like Mercado Libre offering flexible payment solutions.
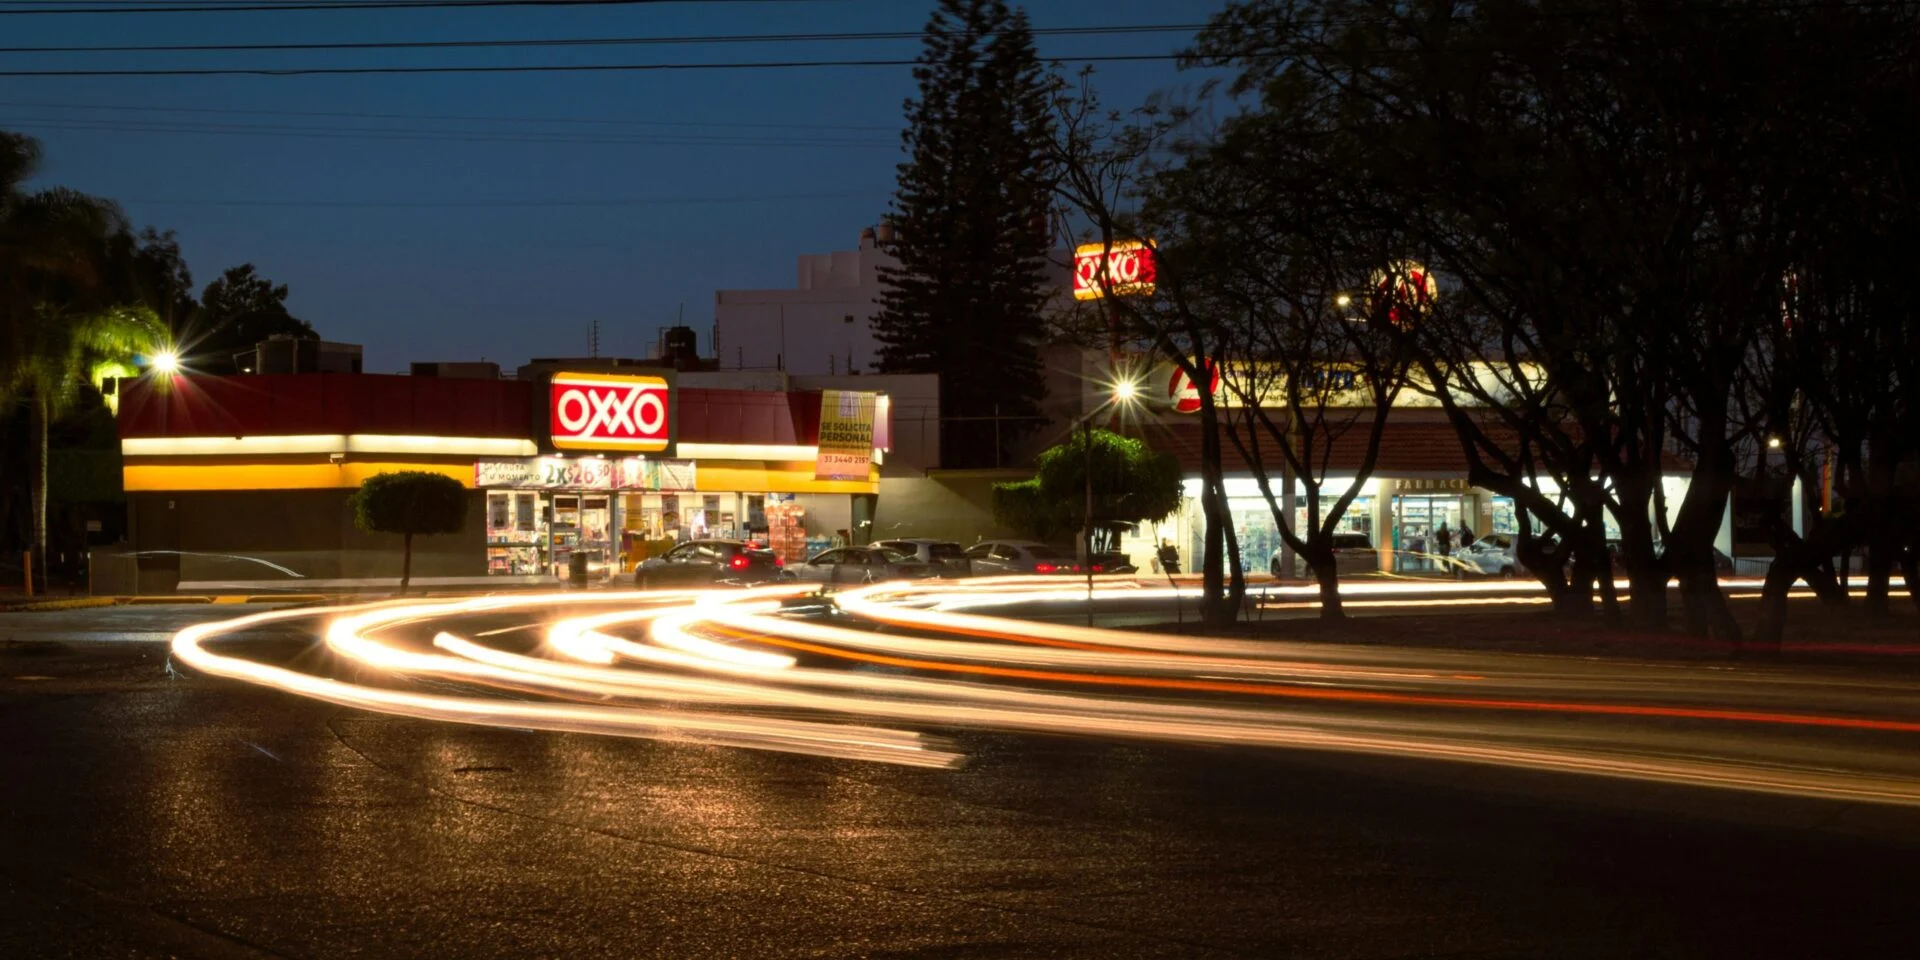
Operators need to recognize that pushing digital payment systems on consumers may not always yield success. De Martino cautions businesses to acknowledge that not all customers will engage with financial systems as desired, especially in cash-dominant markets like Mexico, Colombia, and Peru. To bridge this divide, services like OXXO, a cash-and-voucher payment solution available in Mexico, provide an accessible pathway.
OXXO has established approximately 25,000 locations across the country, allowing most Mexicans to access financial products without the complications of a traditional bank. Customers can utilize cash for various services, from mobile recharges to utility bills, establishing familiarity and trust in the payment process.
Nonetheless, challenges persist in reaching rural areas, where access to financial services is limited. De Martino notes that while ATMs are plentiful in urban centers, many rural communities lack similar resources, underscoring the importance of tailored payment strategies that meet customers where they are.
As competition intensifies in larger markets like Brazil, operators may turn their attention to countries with significant unbanked populations, such as Paraguay. While these markets show promise, high mobile penetration rates across Latin America pave the way for digital wallets and mobile payment innovations. For instance, Yape, a digital platform from Banco de Crédito del Perú, enjoys participation from approximately 70% of adults in Peru.
In Colombia, Nequi, a digital financial service from Bancolombia, accounted for 54% of online retail payments in 2025. Yet, cash remains the primary funding source for 15% of these digital wallet transactions.
Célia highlights the necessity of finding the right partnerships to navigate local market nuances. Collaborating with local payment service providers has proven crucial for businesses looking to adapt to the regional landscape, providing operational advantages while meeting regulatory obligations and reducing risks.
As governments focus on enhancing financial inclusivity, the push for a more digital-friendly approach is evident. Peru's National Financial Inclusion Strategy is a notable case, having halved the country's unbanked population between 2011 and 2024 according to the World Bank.
Despite the momentum towards digital services, operators must approach the underbanked with caution. Distrust of traditional banks is prevalent in parts of the region, while there is a notable trust in AI technologies, which could facilitate improved fraud detection and enhance customer confidence in digital financial systems.
With gambling regulations tightening alongside market growth, integrating digital payment solutions will be essential. Célia points out that in Brazil, the government seeks to minimize cash transactions for anti-money laundering (AML) purposes—a trend likely to resonate throughout Latin America, albeit at varied speeds. By reaching out to the underbanked now, operators stand to gain a competitive edge as the market evolves and relies increasingly on digital payment frameworks.