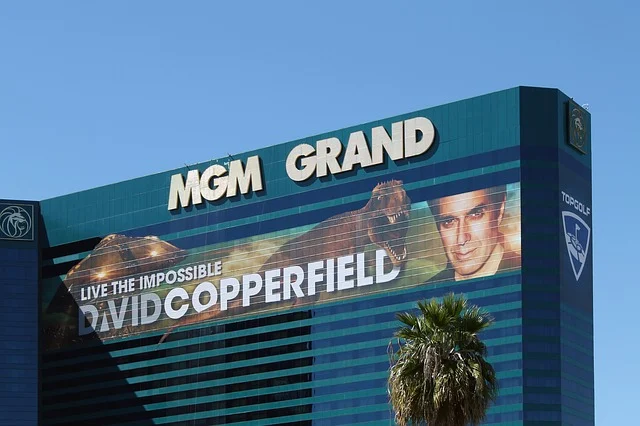
In a significant shift in the corporate landscape, Barry Diller's People Inc recently withdrew an $18 billion offer to secure the 73% of MGM Resorts shares it does not already possess. However, reports indicate that MGM might be contemplating a bid for People Inc instead.
The Wall Street Journal broke the news of this potential turnaround late Thursday, citing insider sources. Following Diller's retraction of the bid, People Inc's share prices have surged by 10% this week. In contrast, MGM's shares have plummeted nearly 15%.
Diller first invested in MGM in 2020 and currently holds a 27% stake in the company, which is estimated to be comparable in value to People Inc’s $3 billion market capitalization, according to the Journal. Upon confirming the termination of negotiations for the MGM acquisition, Diller stated that the "ingredients" of the deal were not aligning as anticipated. Nonetheless, he expressed "total confidence" in MGM and emphasized that People Inc remains "open to and interested in the possibility of a strategic transaction with MGM Resorts."
Neither People Inc nor MGM provided comments on this developing situation.
Diller's interest in MGM stemmed from its tangible assets, a particularly strategic focus in an era increasingly defined by AI and technological advancements. Acquiring MGM would have diversified People Inc’s portfolio and mitigated risks posed to its media and publishing arms due to evolving market conditions.
Conversely, the strategic advantages for MGM in acquiring People Inc, which publishes titles including People magazine and Food & Wine, are less clear. MGM's stock has already seen significant declines, losing a quarter of its value in the last month.
In light of Diller's exit from the acquisition talks, MGM Chairman Paul Salem did not hint at pursuing the deal. He stated that the company has a "clear path to increasing shareholder value" through its existing strategies.
Despite the deal's collapse, analysts continue to hold a positive outlook for MGM. They suggest that challenges related to borrowing costs and regulatory hurdles were likely factors in halting the negotiations, rather than any deficiencies within MGM itself. Macquarie analyst Chad Beynon described MGM's implied enterprise value of approximately $5.9 billion as "a striking discount," while Barry Jonas of Truist sustained a "Buy" recommendation at a price target of $55, well above MGM's current price of about $32.50.