As the Copa Libertadores reaches its climax, excitement fills the air, but so too does frustration for many would-be bettors. Just as the ball meets the back of the net, a new customer rushes to place a last-minute wager, only to be thwarted by the realization that their preferred payment method isn’t accepted. The decisive moment for them has slipped away, leaving betting operators in Latin America grappling with lost transactions and lower conversion rates.
To thrive in this burgeoning market, operators must eliminate payment barriers at this crucial juncture in the customer experience. The Latin American iGaming industry is projected to approach $10 billion by 2028, fueled by newly regulated markets, enhanced connectivity, and a burgeoning population of sports enthusiasts.
However, a significant hurdle persists: the enduring reliance on cash. According to the Worldpay global payments report, cash transactions accounted for 23% of point-of-sale spending in 2025, surpassing the global average by 9%. This trend, however, is not uniform across the region. Countries like Brazil and Chile align more closely with the global average (12% and 16% cash use, respectively), while Colombia and Mexico's dependence on cash skyrockets to 32% and 40% respectively.
Adding to the challenge is the fact that 26% of the population in Latin America remains unbanked. As such, betting operators must offer payment options that align with the financial lives of their potential customers.
A potential solution to this payment gap lies in advancing technology. The fintech sector in Latin America has surged forward following regulatory reforms, leading major countries to adopt frameworks that support the digital financial era. For instance, in Brazil, co-founder and director of Pay4Fun, Ari Célia, notes how commonplace and easily accessible digital bank accounts have become. Users can simply download an app, and even individuals with poor credit histories can obtain a bank account.
Brazil's Pix, a digital payment system overseen by its Central Bank, has rapidly gained traction among gamblers, representing an astounding 96% of gambling transactions in Brazil, as reported by Pay4Fun. This model exemplifies how local payment methods can successfully draw in players previously marginalized by traditional banking systems.
In comparison, Chileans are tapping into formal financial systems thanks to the nation's historical economic stability, resulting in a higher percentage of banked individuals, with debit and prepaid cards making up 32% of online transactions. Yet, trust in financial institutions isn't consistent throughout the region.
Mónica De Martino, a senior payments solutions leader, points out that many Mexicans may avoid institutional banking to keep their financial behaviors private. In addition, many individuals employed in informal job sectors, where cash is predominant, miss out on the protections offered by formal banking due to non-registration. Given this context, a significant portion of their daily transactions continues to be cash-centric.
People often remain skeptical of the hidden costs in banking, such as monthly feesz if cards aren’t used frequently, which can deter them from switching to bank accounts.
Traditionally, banking can introduce delays in transactions, which is problematic for the instant gratification often desired in gambling. As Célia recalls, methods like Boleto took a full day to confirm transactions, which was acceptable back in 2020 but is now seen as unacceptable compared to technologies that can confirm payment transactions in under ten seconds.
The significance of payment mechanisms in the iGaming sector cannot be overstated. Operators must comprehend regional pain points for crafting seamless customer experiences. Past hyperinflation in Argentina led to issues for international payment services, but with inflation now easing, players are cautious about holding onto Pesos, favoring alternatives that provide financial safety. Digital wallets, such as Mercado Pago, allow users to earn returns on balances and access funds easily for daily expenses.
The rising buy now, pay later options, projected to reach $6.19 billion by 2030, show the growing acceptance of digital finance. To successfully engage with underbanked populations, operators must respect their existing behaviors and financial habits while motivating them toward digital solutions.
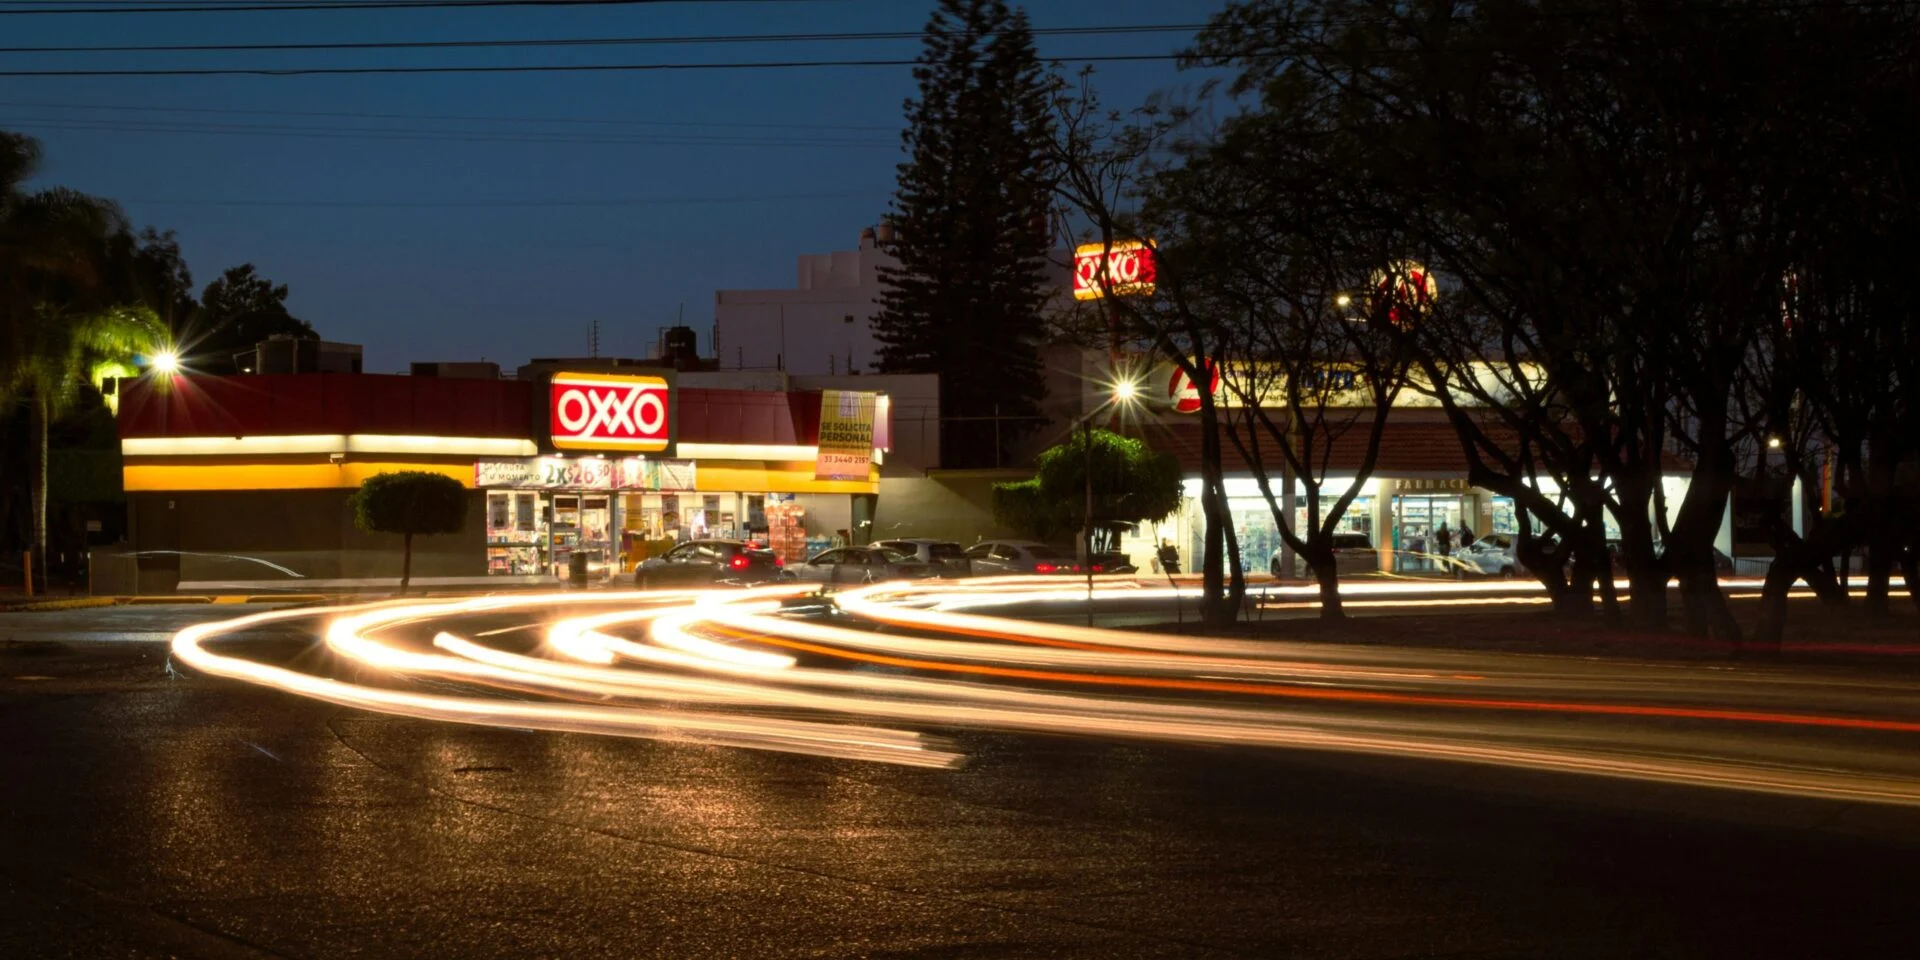
In countries like Mexico, where cash remains dominant, OXXO presents an instructive case. As De Martino notes, customers can access financial products without setting foot in a bank, either by downloading an app or obtaining a debit card from an OXXO location within minutes. This system facilitates a smooth transition for customers moving between cash and digital payment methods, fortifying their relationship with familiar service environments where personal relationships may foster trust.
However, while urban areas display a concentration of banking services, rural regions often face a lack of access, underscoring the complexity of achieving financial inclusion. OXXO has adapted by expanding its presence to over 25,000 outlets in Mexico, significantly increasing financial access for the population. Operators keen on growth must tailor payment strategies to local infrastructure and consumer habits.
As Latin America’s largest markets, particularly Brazil, become more competitive, operators may seek growth in countries like Paraguay, which is home to many unbanked individuals. Despite high mobile penetration, cash still plays a part in transactions. Digital platforms like Nequi account for 54% of online retail payments in Colombia, yet cash continues to be the source for 15% of transactions.
To effectively build strong connections with diverse player markets, operators must cultivate local partnerships, as Célia did in Argentina with Pay4Fun and Pix. These partnerships pave the way for navigating local regulations and enhancing financial security through technology.
Government efforts in Latin America to improve financial accessibility, such as Peru's National Financial Inclusion Strategy, underscore a regional shift towards digitization. Although confidence in traditional banking remains low, operators can leverage the growing trust in artificial intelligence to boost security in digital transactions and streamline the betting experience.
With gambling regulations tightening in response to market expansion, approaches to underbanked populations must be carefully devised. Those who prioritize connecting with financially underserved groups today will be better positioned for success as regulatory pressures favor digital transactions in the future.