On Thursday, Rank Group announced a 5% growth in like-for-like Net Gaming Revenue (NGR) for the first quarter of the 2026/27 financial year, reaching £216.1 million ($286.5 million) for the three months ending September 30, 2026. The company attributed this steady revenue growth to performance across various channels, despite changing market conditions. Rank described the quarter as a "strong start to the new financial year" and anticipates that, provided the current UK tax framework remains intact, improved operating profits will align with market projections for the entire year.
In the trading update, CEO Richard Harris raised concerns about the risks posed by a potential increase in the UK’s Machine Games Duty (MGD), which could be outlined in the upcoming autumn budget. He emphasized that elevated MGD rates could lead to increased operating expenses, ultimately threatening the viability of gambling venues. Harris stated, "Any increase to Machine Games Duty will increase costs, reduce venue viability, lead to venue closures and job losses, reduce tax receipts and halt investment." He further mentioned that HM Treasury acknowledged these economic considerations last year, suggesting that casinos and bingo halls could contribute to the government’s growth strategy if conditions remain favorable.
A recent analysis from Deutsche Bank positioned Rank at significant risk if MGD rates rise. The bank estimated that an increase in duty could cost the company an additional £35 million annually, amounting to around 44% of its expected EBIT for 2028 and approximately 17% of EBITDA in the short term, even accounting for some mitigation. This led to a downgrade of Rank from a "buy" to a "hold" rating.
Rank’s digital division achieved a 6% rise in like-for-like NGR, totaling £64.9 million, primarily driven by its UK digital segment, including growth from Mecca’s online offerings. Internationally, digital NGR grew by 4%, demonstrating strength in global markets.
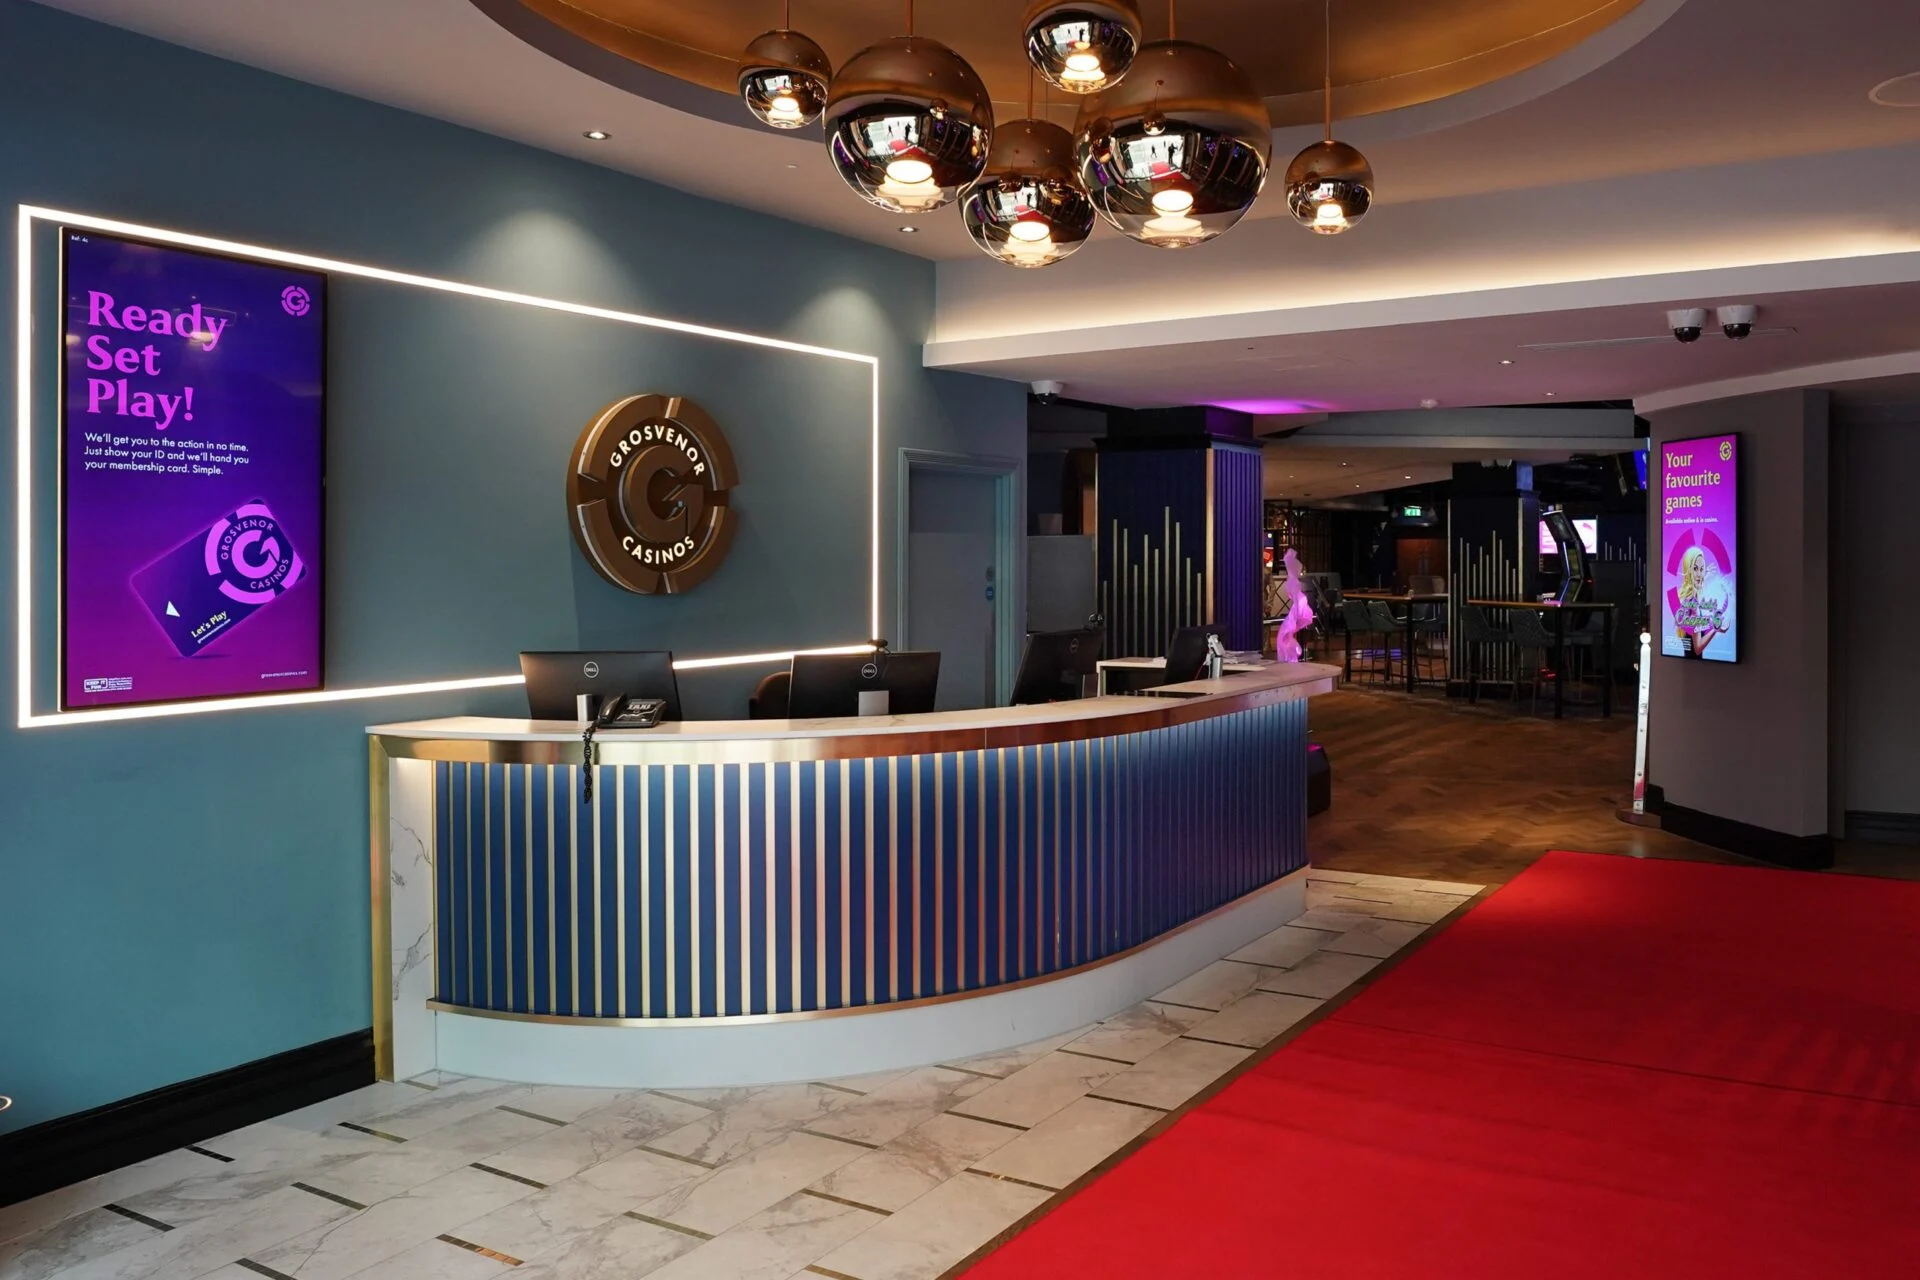
Meanwhile, Grosvenor Casinos reported a 6% increase in like-for-like NGR to £108.1 million, supported by a 1% boost in visits and a 5% rise in spend per visit, indicating enhanced customer engagement. In contrast, Mecca bingo venues maintained stable NGR at £32.2 million despite a 3% decline in visitor numbers, which was partly attributed to an unusually hot weather period in the UK; however, spending per visit rose by 3%.
Rank’s operations in Spain, through its subsidiary Enracha, showed a 7% increase in like-for-like NGR to £10.9 million, largely due to an 11% rise in electronic gaming revenue, indicating positive growth in that market.
The quarter also saw a notable 14% increase in revenue from gaming machines, while table gaming and electronic gaming experienced more modest growth rates of 3% and 5%, respectively. Rank expressed confidence in further optimizing its machine offerings to enhance revenue.
Conversely, the company announced the closure of three venues located in Swansea, Reading Central, and Sunderland, citing their lack of economic viability in the medium term. Earlier this year, Rank projected an underlying operating profit of at least £76 million for the year concluded in June 2026, and reported a 6% increase in like-for-like NGR, nearing £834.1 million for the annual period. This growth trend continued into the fourth quarter, reflecting a 6% increase compared to the previous year with a reported NGR of £208.9 million.
Looking ahead, Rank Group is set to release its interim financial results for the six months ending December 31, 2026, on January 28, 2027.