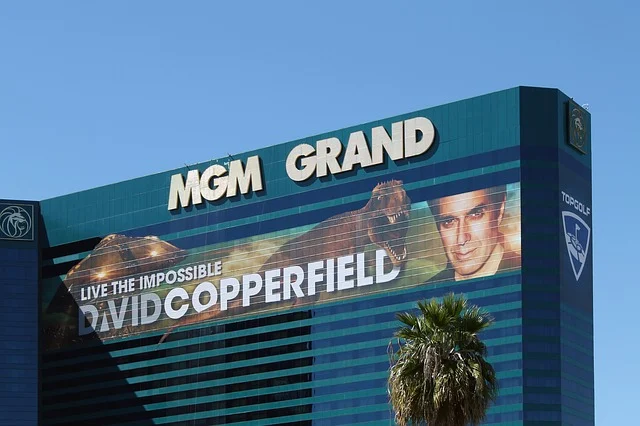
This week, Barry Diller's People Inc withdrew its $18 billion proposal to acquire the 73% stake in MGM Resorts that it does not already own. In light of this development, new reports suggest that MGM is now considering a bid for People Inc instead.
The Wall Street Journal reported late Thursday on this possible shift in plans, citing sources familiar with the situation. Following the announcement of the rescinded offer and the potential pivot, People Inc's stock has risen by 10% this week, whereas MGM's shares have dropped nearly 15% during the same period.
Diller began investing in MGM in 2020 and holds a 27% stake, an investment believed to be equivalent to People’s market capitalization of approximately $3 billion, according to the Wall Street Journal. In a statement confirming the end of takeover discussions, Diller noted that the “ingredients” of the deal were not “coming together in the way we had hoped.” However, he expressed “total confidence” in MGM and stated that People Inc remained “open to and interested in the possibility of a strategic transaction with MGM Resorts.”
Both companies declined to comment on the situation when approached by media outlets.
Diller’s interest in MGM was driven by the desire to acquire its tangible assets within an evolving business landscape where AI and technology play increasingly significant roles. Acquiring MGM could have allowed his company to diversify its portfolio and mitigate potential impacts on its media and publishing sectors from AI advancements.
On the other hand, it is unclear what strategic benefits MGM would gain from acquiring People Inc, which operates well-known brands such as People magazine and Food & Wine. MGM's stock has recently faced challenges, losing about 25% of its value in the past month.
MGM's Chairman, Paul Salem, did not indicate any intention to pursue an acquisition after Diller's exit from negotiations. He stated on Wednesday that the company has a “clear path to increasing shareholder value” through its existing strategies.
Despite the setbacks, analysts remain optimistic about MGM. Market consensus suggests that the obstacles to the deal were more about borrowing costs and regulatory issues rather than any fundamental concerns with MGM itself. Macquarie analyst Chad Beynon noted that MGM's implied enterprise value of around $5.9 billion represents “a striking discount,” while Barry Jonas of Truist maintained a “Buy” rating with a target price of $55, significantly higher than its current price of about $32.50.