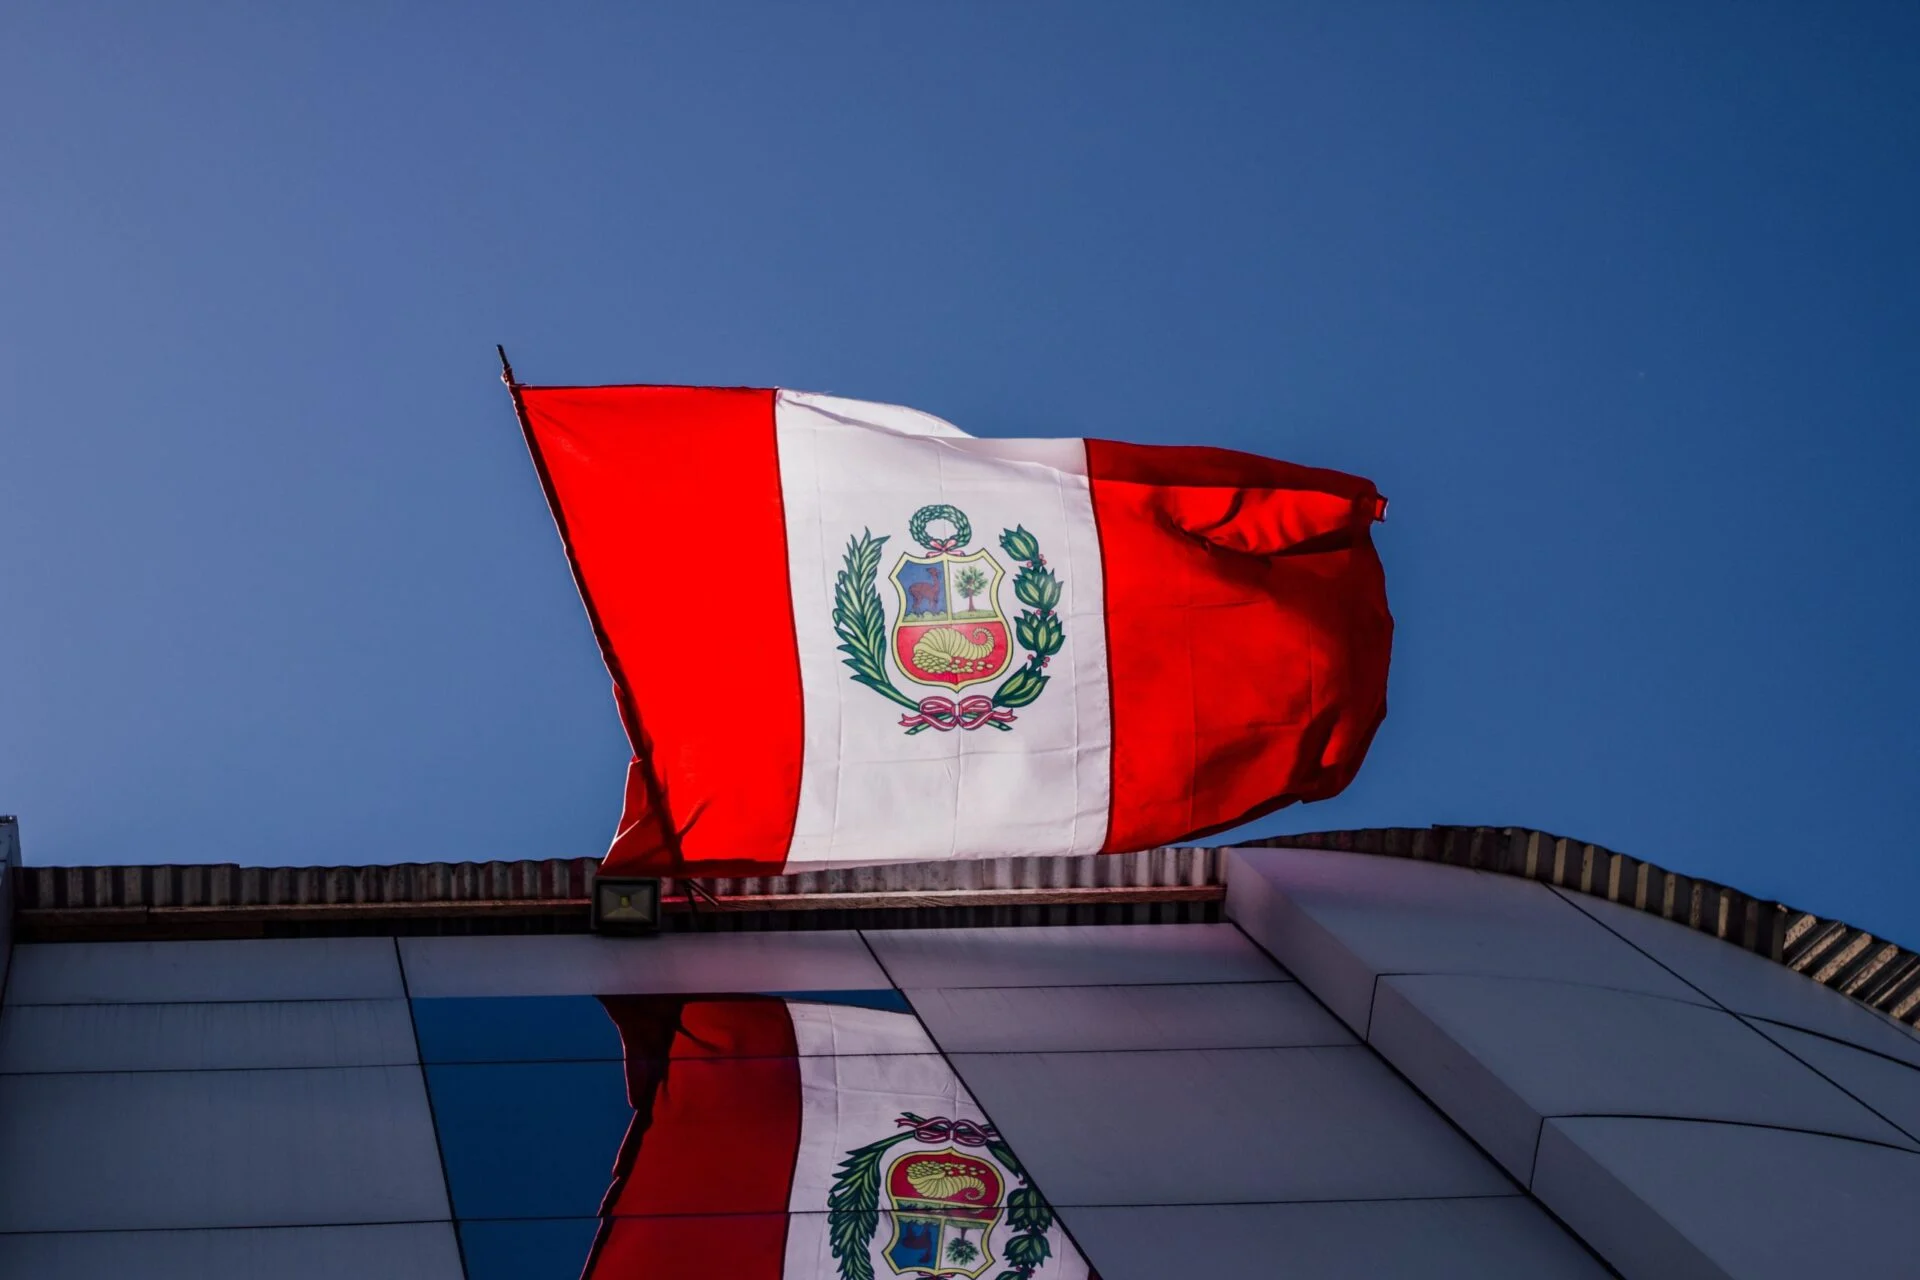
The regulated gaming market in Peru officially launched in February 2024, quickly drawing numerous international operators. This competitive environment includes established local players like Apuesta Total, which is currently the market leader.
Jennyfer Escobar, Stake’s Peru country manager, describes the Peruvian market as one of the most competitive in Latin America. "In the early stages, competition was largely driven by marketing investment, including advertising and sponsorships,” she said. “Today, product quality, platform performance, and overall user experience have become much stronger differentiators. Players are more informed, have higher expectations, and will switch brands if those expectations aren’t met."
Stake entered the Peruvian market in 2024, while Betsson has been operating there since 2008, navigating the market’s evolution both before and after regulation. Andrea Rossi, the commercial director for Southern Europe and Latin America at Betsson, notes that Peru's market is "quite polarized," with a few operators dominating and others lagging behind. He comments, "We have seen fierce competition. We have been there for a long time, and we have our positioning quite cemented. But we need to look at ourselves and keep improving, embracing the Peruvian culture and adapting to the market with a localized approach."
The competition between local and international brands has intensified. Local Peruvian firms possess cultural knowledge that allows them to connect with players, but they face challenges from international operators with greater scale in technology and capital. Ramiro Atucha, founder and CEO of Atucha Strategic Advisory, emphasizes the importance of true localization. “When we talk about localization, we’re not just talking about language or a game featuring Machu Picchu. We must understand players' histories and preferences. It’s essential to recognize their experiences, as understanding what players enjoy can help bridge gaps in service."
Local operators are striving to enhance their technology by collaborating with prominent suppliers. Yet, Atucha points out that larger platforms entering Latin America often prioritize partnerships with tier 1 operators, sidelining smaller companies. "Whatever you would consider a tier 3 or tier 2 operator in emerging markets can eventually become a tier 1 operator," he mentioned, citing the example of EstrelaBet, which has experienced significant growth.
According to Atucha, global scale is advantageous only when paired with local perspectives. Betsson's deep-rooted experience since 2008 in Peru provides them with an edge. “We have seen it all,” says Rossi. He highlights that Betsson's success is attributed to multiple factors, including significant investment in Peru, contributing to 36% of their Q2 revenue of €310.2 million. “Peru is our legacy,” he asserts, emphasizing their commitment to developing tailored products and understanding local markets.
Similarly, Stake is striving to balance its global presence with an understanding of local dynamics. With licenses in Colombia, Brazil, Peru, and Mexico, as well as Buenos Aires, Argentina, Escobar believes success in Peru requires more than just a global approach. “While we have world-class technology and a market-leading product, we’ve heavily invested in understanding Peruvian players, forging local partnerships, and tailoring our marketing strategies to local preferences,” she stated.
Peru’s regulatory framework is seen as one of the strongest in Latin America, fostering a transparent market environment. Rossi considers the rollout of regulations to be highly positive, citing their flexibility and the strong relationships between regulators and operators. Escobar observes that the nascent regulated market presents a promising opportunity for operators due to substantial player engagement and digital adoption.
However, challenges remain, particularly with the introduction of a 1% selective consumption tax (ISC) on online betting, effective from July 1, 2025. Atucha cautions that initial tax measures often appear favorable but may later burden licensed operations. He equates this phenomenon to "boiling a frog," where gradual increases can lead to significant challenges. Rossi warns that the new ISC could discourage channelization to licensed offerings, leading to potential increases in black market engagement, as illegal operators are not subject to such taxes.
Both Atucha and Rossi agree that excessive taxation could harm growth, with Atucha drawing parallels to issues faced by mobile gaming regulations in the UK and Germany. He argues that offshore operators often represent well-known brands rather than untraceable entities, challenging the narrative around player risk.
As operators navigate these hurdles, they are now tasked with sustaining growth in a competitive landscape. Escobar anticipates the emergence of a more developed market structure, highlighting that operators must adapt their strategies beyond mere marketing to focus on innovation and customer experience. While Rossi views Peru as a mature market due to its historical tolerance of betting, he recognizes opportunities for growth through mobile penetration and attracting new digital consumers. “It’s our responsibility to educate newcomers in online gaming to always play responsibly,” he concludes.